Medtech in 2026: How Pricing Pressure, Tariffs and Platform Competition Are Redrawing North American Supply Chains
James Wilson
Industry Analyst
September 13, 2026
DATELINE: NA TRADE WIRE
"Clarivate's 2026 medtech outlook identifies five structural forces reshaping device manufacturing, sourcing and commercial strategy — with direct consequences for cross-border trade, logistics and industrial investment across the United States, Canada and Mexico."
Medtech in 2026: How Pricing Pressure, Tariffs and Platform Competition Are Redrawing North American Supply Chains
Subheadline: Clarivate's 2026 medtech outlook identifies five structural forces — volume-based procurement in China, the migration of procedures to ambulatory settings, tariff-driven manufacturing shifts, GLP-1 ripple effects and platform-based competition — that will shape cross-border investment, logistics and industrial policy across the United States, Canada and Mexico.
---
Executive Summary
The global medical technology sector is entering a period in which competitive advantage depends less on product performance alone and more on cost structure, manufacturing geography, supplier concentration and portfolio positioning.
Clarivate's Medtech Trends to Watch 2026 isolates five structural forces: the expansion of mainland China's volume-based procurement (VBP) regime and its effect on global price expectations; the migration of procedures into outpatient and ambulatory surgical center (ASC) settings under the U.S. Centers for Medicare & Medicaid Services' 2026 payment rules; tariff exposure and geopolitical volatility pushing manufacturers toward multi-region production footprints; the clinical and commercial ripple effects of GLP-1 therapies; and the shift toward platform-based competition built on robotics, imaging, navigation and digital workflow software.
For North America, these forces converge on issues that are fundamentally about trade and industrial geography: border cost, supplier diversification, site-of-service distribution, and where advanced device manufacturing capacity is located and financed. The strategic implication is that trade policy, industrial policy and product strategy can no longer be managed as separate workstreams.
---
Introduction
The medical device industry has long been treated as a segment of healthcare. That framing is increasingly inadequate. Device manufacturers are, in practical terms, advanced manufacturing businesses with globally distributed supplier networks, cross-border production flows, tariff exposure and capital allocation decisions that resemble those of the automotive or semiconductor sectors.
The Clarivate outlook published in April 2026 makes this convergence explicit. Three of its five identified trends — global pricing pressure originating in China's procurement regime, tariff and supply chain volatility, and platform-driven competition — sit squarely within the domain of trade and industrial strategy rather than clinical practice.
For exporters, importers, contract manufacturers, logistics providers and investors operating across the United States, Canada and Mexico, the relevant question is not whether medtech demand grows. It is where that demand will be served from, at what cost, and under which regulatory and tariff conditions.
---
Main Analysis
1. Volume-Based Procurement Abroad Resets Global Price Expectations
Mainland China's national volume-based procurement program was originally designed to expand patient access and curb device costs. According to Clarivate, it has evolved into a market-structuring mechanism, with the latest round introducing more sophisticated anchor-price logic, deeper price compression and allocation systems that favor domestic manufacturers.
The significance for North American firms extends beyond participation in China. VBP has become a reference point for payers, procurement bodies and competitors elsewhere, influencing assumptions about price, volume and competitive positioning in markets far from the program's origin. Companies that treat VBP as a localized policy risk misread its function as a global price-setting signal.
Why it matters: Portfolio strategy, reimbursement positioning and manufacturing cost structure all become more consequential when price expectations are being reset by procurement design rather than by clinical differentiation.
2. Site-of-Service Migration Reshapes Demand — and Distribution
The continued migration of procedures from hospitals to outpatient settings remains one of the more durable medtech trends. CMS' 2026 Hospital Outpatient Prospective Payment System (OPPS) and ASC Payment System final rule expands the ASC Covered Procedure List and phases out the inpatient-only list, opening the door for higher-acuity procedures — cardiac ablation among them — to move into lower-cost settings where clinically appropriate.
This builds on long-running patterns in orthopedics and general surgery, where ambulatory surgical centers have become central to growth strategies for both providers and manufacturers.
The operational consequence is a different demand map. Smaller, more numerous, more geographically dispersed procedure sites require different inventory positioning, different distribution economics and different service models than concentrated hospital systems. For logistics providers and distributors, the shift changes shipment profiles, order frequency and working capital requirements.
Why it matters: Medtech commercial models, economic value propositions and product design must adapt to a more fragmented set of service sites.
3. Tariffs and Trade Volatility Push Manufacturing Toward Multi-Region Footprints
Supply chain resilience has moved from contingency planning to strategic imperative. Clarivate identifies tariff exposure, geopolitical factors and fluctuating material costs as pressures challenging long-standing assumptions about where and how devices should be produced.
Manufacturers are responding by diversifying sourcing, re-evaluating business strategies and pursuing more flexible multi-region manufacturing footprints. Larger manufacturers are using scale, integration and technology investment to buffer against volatility — a dynamic that could further reshape competitive positioning across device categories.
This is the trend with the most direct North American trade relevance. Cost structures, supplier concentration, manufacturing geography and portfolio rebalancing are becoming determinants of competitive advantage, not secondary considerations behind product performance.
Why it matters: Decisions about plant location, supplier qualification and inventory buffers are now also decisions about tariff exposure and border risk.
4. GLP-1 Adoption Redraws Clinical and Device Demand Pathways
The rapid adoption of glucagon-like peptide-1 (GLP-1) receptor agonists is altering how patients and clinicians approach weight management and related comorbidities. Bariatric surgery remains the most effective intervention for substantial weight loss, but GLP-1s have expanded quickly in popularity, changing referral patterns and influencing demand across adjacent device categories.
The impact is not uniform. Some bariatric procedures face sharper volume pressure than others, and downstream effects across diabetes care, sleep apnea and cardiovascular monitoring are only beginning to emerge.
For manufacturers, the exposure is portfolio-specific rather than sector-wide. For investors and suppliers, it is a reminder that clinical pathway shifts can reprice entire product lines faster than capital investment cycles can respond.
Why it matters: Metabolic disease management is shifting in ways that will redistribute demand across multiple device markets and clinical pathways.
5. Platform Competition Rewrites the Value Proposition
Robotics, imaging, navigation and digital workflow software are no longer adjuncts to procedures. They are becoming the architecture around which integrated ecosystems are built, supporting clinical planning, surgical execution and postoperative care.
Companies are investing in platform architectures intended to anchor entire service lines, deepen customer relationships and support data-driven value propositions. Emerging open-platform systems are adding flexibility and creating new competitive dynamics, including pressure on closed, proprietary ecosystems.
Why it matters: Platform-based competition changes how value is delivered, how customers are retained and how long-term strategic advantage is constructed — and it raises the stakes on software capability, data governance and interoperability.
---
Trade Impact
The five trends interact with international trade through several distinct channels.
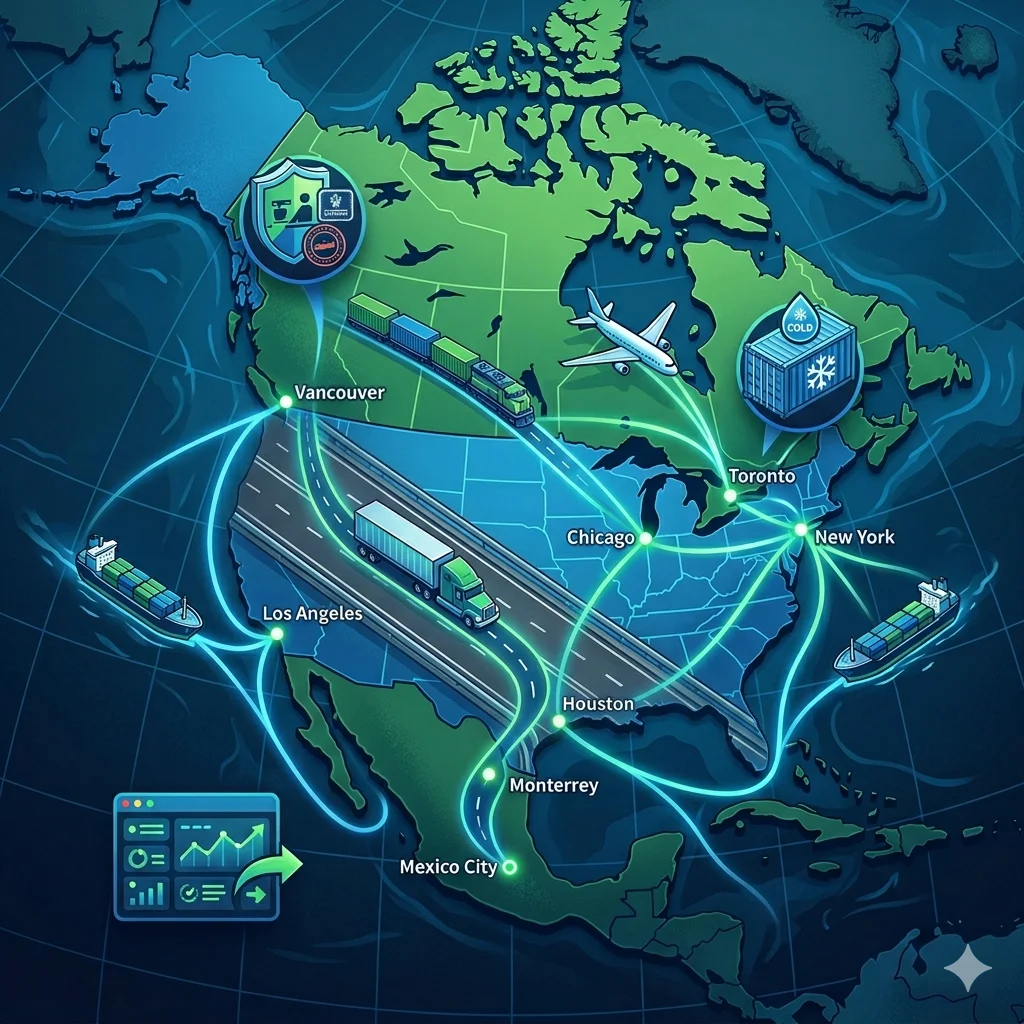
Supply chains and manufacturing. Tariff exposure and material cost volatility accelerate the case for multi-region production. For North America, that can mean incremental investment in existing device manufacturing clusters in Mexico and the United States, but it also raises qualification, validation and regulatory approval costs that can offset tariff savings.
Cross-border commerce and logistics. The shift toward ambulatory settings fragments demand across more locations, changing freight profiles, cold chain requirements and inventory positioning. Cross-border logistics providers serving medical device flows will face pressure to support higher-frequency, lower-volume shipments alongside existing bulk distribution.
Corporate strategy and investment. Portfolio rebalancing — driven by procurement-driven price compression on one side and GLP-1-related demand shifts on the other — is likely to redirect capital expenditure and merger activity toward higher-margin, platform-adjacent categories.
SMEs, exporters and importers. Smaller suppliers are disproportionately exposed to tariff volatility and to customer demands for dual sourcing. Component makers and contract manufacturers that cannot offer geographic redundancy may find themselves displaced from qualified supplier lists.
Trade finance and working capital. Longer, more complex supply routes and higher inventory buffers increase working capital intensity. For mid-sized suppliers, access to trade finance becomes a competitiveness issue rather than a back-office function.
Economic resilience. Diversification reduces single-point-of-failure risk but raises aggregate cost. The policy question is whether resilience is treated as a cost to be minimized or a capability to be underwritten.
---
Regional Perspective
United States. The 2026 CMS payment rules reinforce the migration of procedures to ambulatory settings, reshaping domestic demand geography and strengthening the case for distribution and service infrastructure outside traditional hospital corridors. Tariff policy simultaneously raises the cost of imported components and finished devices, sharpening interest in domestic and nearshore production.
Mexico. Mexico's established medical device manufacturing base — concentrated in border and central industrial corridors — is a natural beneficiary of diversification strategies. Realizing that benefit depends on supplier depth, engineering talent, regulatory capacity and logistics reliability, not on proximity alone.
Canada. Canadian strengths in imaging, digital health and research commercialization position the country to participate in platform-based competition, but Canadian firms remain dependent on access to U.S. capital and customers. Cross-border regulatory alignment and data governance frameworks will shape how much of that value is captured domestically.
USMCA and integration. The agreement provides the tariff-preference architecture within which device supply chains are reorganized. Its rules of origin, customs procedures and review mechanisms determine whether nearshoring translates into genuine regional value addition or simple rerouting of foreign content.
Competitiveness and diversification. North America's position depends on whether the region can combine cost discipline with innovation leadership. Price compression originating abroad and platform competition originating in the technology sector squeeze from both directions.
---
Future Outlook
Over the next three to five years, several developments appear structurally likely, though their timing and magnitude remain uncertain.
Trade integration and diversified sourcing. Expect continued movement toward dual-region and multi-region manufacturing among larger device manufacturers, with qualified supplier networks expanding across North America. Smaller suppliers will face rising compliance and redundancy costs.
Nearshoring and industrial policy. Medical devices are likely to remain a priority category in North American industrial policy discussions, given their link to health security and advanced manufacturing capability. Incentive design will matter more than incentive size.
Artificial intelligence and advanced manufacturing. AI-enabled inspection, predictive maintenance and supply chain forecasting are plausible productivity levers for device production, but adoption will be constrained by validation requirements and regulatory expectations in a highly regulated manufacturing environment.
Infrastructure and logistics. Ports, rail corridors, industrial parks and cold chain capacity across the United States, Canada and Mexico will need to accommodate more distributed, higher-frequency device flows.
Energy, critical minerals and materials. Device manufacturing depends on specialised materials and components whose supply is concentrated in a limited number of jurisdictions. Materials security is likely to become a more prominent element of device supply chain strategy.
Digital economy and platform governance. As platforms become central to clinical workflows, questions of data residency, interoperability and cross-border data transfer will intersect directly with trade policy.
North America's global position. The region's advantage lies in combining manufacturing capability, regulatory coherence and innovation capacity. Whether that combination holds depends on decisions made in procurement offices, plant planning meetings and trade negotiations over the next several years.
---
Key Takeaways
- Clarivate identifies five structural forces shaping medtech in 2026: China's VBP expansion, site-of-service migration, tariff and supply chain pressure, GLP-1 ripple effects, and platform-based competition.
- Three of the five trends are principally trade and industrial strategy questions rather than clinical ones.
- Volume-based procurement functions as a global price-setting signal, not merely a China-specific policy.
- U.S. payment rule changes are redistributing procedure volumes toward ambulatory settings, altering distribution and inventory economics.
- Tariff exposure is driving multi-region manufacturing footprints, with direct consequences for investment, SME suppliers and trade finance.
- Platform competition raises the strategic value of software, data and interoperability relative to standalone device performance.
- For North America, the central competitive question is whether resilience investments translate into durable capability or only higher costs.
---
Conclusion
The medtech sector's 2026 agenda is not confined to hospitals and laboratories. It runs through customs procedures, supplier qualification processes, industrial parks and port corridors. Pricing pressure originating in procurement policy, tariff volatility at the border, clinical pathway shifts and platform-driven competition are converging on the same set of decisions: where to manufacture, how to source, how to distribute and where to invest.
For manufacturers, exporters, importers, logistics providers and investors across the United States, Canada and Mexico, treating medtech as a trade and industrial story is no longer optional. The companies and jurisdictions that align product strategy with supply chain geography — and with the policy environment that governs both — will be better positioned as the decade progresses.
---
SEO Keywords
North America trade, USMCA, cross-border trade, medical device manufacturing, medtech trends 2026, supply chain resilience, nearshoring, foreign direct investment, industrial policy, trade policy, advanced manufacturing, logistics, volume-based procurement, ambulatory surgical centers, GLP-1, critical minerals, digital economy, business strategy, regional trade, economic development, North American economy
---
Sources
- Clarivate, "5 medtech trends to watch in 2026," April 28, 2026 — https://clarivate.com/life-sciences-healthcare/blog/5-medtech-trends-to-watch-in-2026
- Clarivate, Medtech Trends to Watch 2026 (e-book landing page) — https://clarivate.com/life-sciences-healthcare/lp/medtech-trends-to-watch-in-2026/
- U.S. Centers for Medicare & Medicaid Services, Hospital Outpatient Prospective Payment System and Ambulatory Surgical Center Payment System (2026 final rule reference) — https://www.cms.gov/
Trade Metrics
Related Datasets
Q4 Cross-Border Logistics Report
PDF • 4.2 MB
Automotive Parts Supply Chain Index
CSV • 1.1 MB